LEGISLATIVE FISCAL ESTIMATE
SENATE, No. 986
STATE OF NEW JERSEY
219th LEGISLATURE
DATED: MAY 5, 2021
SUMMARY
|
Synopsis: |
Establishes surplus revenue reserve account in the Property Tax Relief Fund if certain levels of unanticipated gross income tax revenue are collected. |
|
Type of Impact: |
Potential reallocation of unrestricted surplus revenues from Property Tax Relief Fund to restricted Surplus Gross Income Tax Revenue Account. |
|
Agencies Affected: |
Department of the Treasury. |
|
Office of Legislative Services Estimate |
||||
|
Fiscal Impact |
|
Annual |
|
|
|
State Revenue |
Potential reallocation of surplus revenues from Property Tax Relief Fund to Surplus Gross Income Tax Revenue Account |
|
||
|
|
|
|||
· The Office of Legislative Services (OLS) notes that the bill establishes a Surplus Gross Income Tax Revenue Account in the Property Tax Relief Fund. However, the Surplus Gross Income Tax Revenue Account is funded through existing gross income tax revenues in the event there is a surplus. The bill does not establish a new revenue source.
· The bill may restrict future Legislatures from enacting an increase in the gross income tax rate or modifying the gross income tax in a manner that would generate more gross income tax revenue.
BILL DESCRIPTION
This bill establishes a Surplus Gross Income Tax Revenue Account in the Property Tax Relief Fund to serve as a “rainy day fund” for property tax relief programs and State Aid programs that offset local property taxes. The State Treasurer is required to credit to the Surplus Gross Income Tax Revenue Account, on or before December 31 annually, an amount equal to one-half of the excess gross income tax revenue collected during the preceding fiscal year if actual gross income tax revenues exceed the Governor’s certified revenues by more than six percent.
Balances in the Surplus Gross Income Tax Revenue Account may be appropriated by the Legislature: 1) if anticipated gross income tax revenues are estimated to be less than the Governor’s certification; 2) to offset gross income tax revenue declines instead of increasing the gross income tax rate or modifying the gross income tax; or 3) for meeting the costs of any emergency identified by the Governor that is within the purposes of the Property Tax Relief Fund.
If in any fiscal year there is enacted an appropriation from the Surplus Gross Income Tax Revenue Account, the Legislature is prohibited from imposing any increases in existing gross income tax rates or gross income tax modifications having the effect of increasing gross income tax revenues. However, if gross income tax revenues decline by at least two percent of the total available gross income tax revenues as certified by the Governor, the Legislature may increase gross income tax rates or modify the gross income tax, and the balances in the Surplus Gross Income Tax Revenue Account may be appropriated in any other manner as found to be in the best interests of the fiscal condition of the Property Tax Relief Fund.
FISCAL ANALYSIS
EXECUTIVE BRANCH
None received.
OFFICE OF LEGISLATIVE SERVICES
The OLS notes that the bill establishes a Surplus Gross Income Tax Revenue Account in the Property Tax Relief Fund. However, the bill does not establish a new revenue source; the account is funded through existing gross income tax revenues in the event there is a surplus. If actual gross income tax revenues deposited into the Property Tax Relief Fund exceed the Governor’s certified gross income tax revenues for a given fiscal year by more than six percent of the certified amount, half of the excess is to be deposited into the account.
For example, the amount of gross income tax revenue certified by the Governor for FY 2020 was $16.5 billion. In order for the account to be eligible for a credit, the actual amount of revenue deposited from the gross income tax during FY 2020 had to exceed the certified amount by more than six percent. Thus, approximately $17.5 billion, an amount equal to $1.0 billion above the certified amount, would be necessary in order for the account to be eligible to receive the credit. The deposit would be equal to half of the excess, or about $500 million. The actual variance between the certified amounts and audited collections has not exceeded six percent at any point during the past six fiscal years (Figure 1).
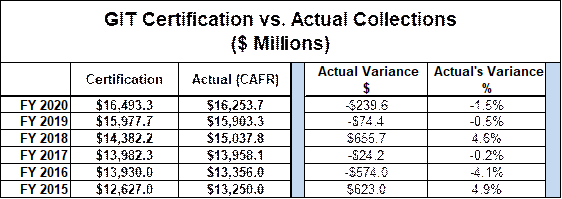
Figure 1
The bill may restrict future Legislatures from enacting an increase in the gross income tax rate or modifying the gross income tax in a manner that would generate more gross income tax revenue. The restriction applies only in a fiscal year during which an appropriation is made from the account. However, if gross income tax revenue declines by at least two percent of total available gross income tax revenue as certified by the Governor, the Legislature may increase gross income tax rates or modify the gross income tax. The balances in the account may then be appropriated in any other manner as found to be in the best interests of the fiscal condition of the Property Tax Relief Fund.
|
Section: |
Revenue, Finance and Appropriations |
|
Analyst: |
Revenue Analyst |
|
Approved: |
Thomas Koenig Legislative Budget and Finance Officer |
This legislative fiscal estimate has been produced by the Office of Legislative Services due to the failure of the Executive Branch to respond to our request for a fiscal note.
This fiscal estimate has been prepared pursuant to P.L.1980, c.67 (C.52:13B-6 et seq.).